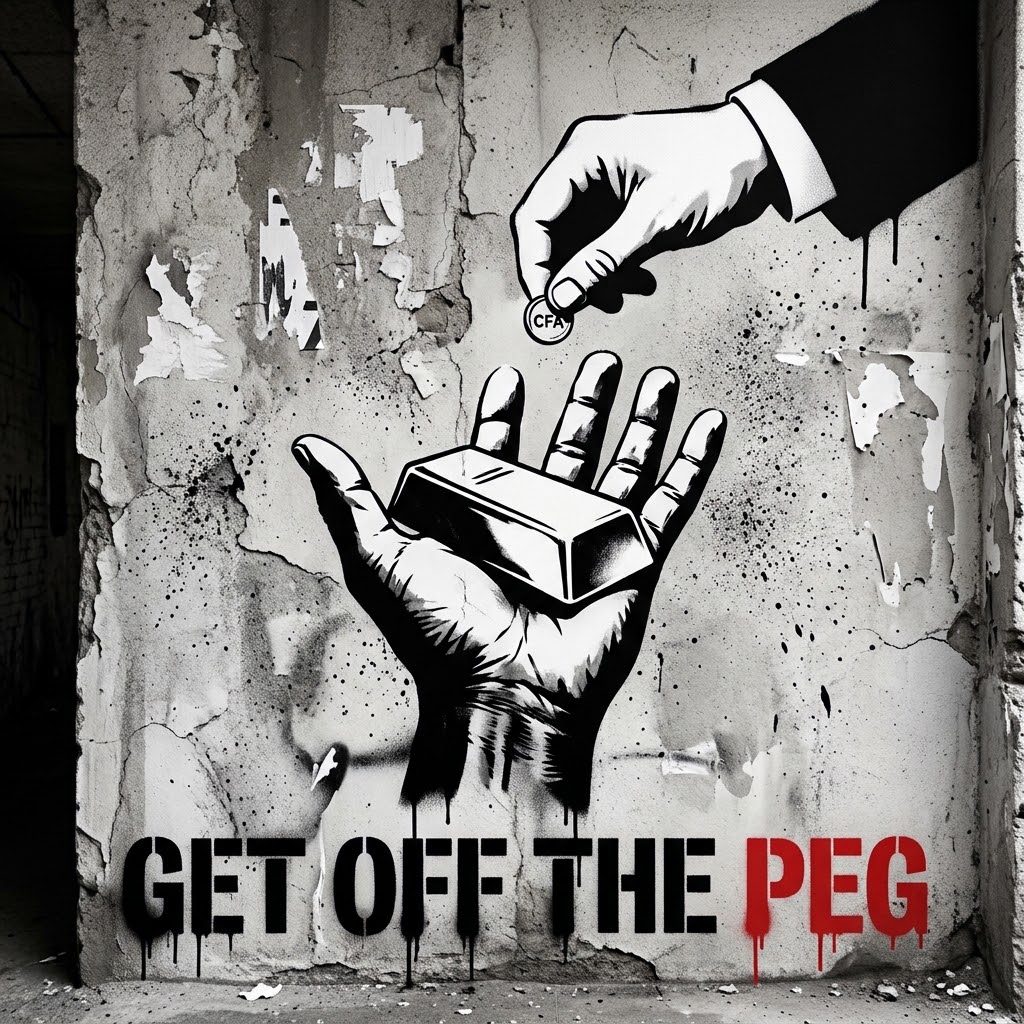
Get Off the Peg: The CFA Franc Is Not a Monetary Problem. It Is a Wages Problem.
Burkina Faso mines gold, sells it in dollars, receives CFA issued in Paris at a rate Ouagadougou does not set, and pays its workers in the result. This is not an abstract currency arrangement. It is a remuneration cycle. And the fix is simpler than anyone in power wants you to believe.
A woman recently made a claim that stopped the commentary class in its tracks. France, she argued, is facing economic difficulty because it can no longer extract African resources with the ease it once did. The Sahel juntas expelled French forces. Burkina Faso moved to reclaim control of its gold industry. Mali and Niger severed the military arrangements that had, for six decades, secured French commercial access behind a diplomatic veneer. And France, she concluded, is feeling the consequences.
The commentary class dismissed her. Economists reached for their frameworks. Politicians reached for their talking points. But she was not wrong. She was, in fact, describing the surface of something that runs considerably deeper. Because the story of France and African resources is not primarily a story about military bases or mining licences. It is a story about a monetary architecture that has, since 1945, ensured that African productive labour was systematically undervalued in the currency through which it was paid. That architecture has a name. It is the CFA franc. And the mechanism through which it operates is not, as most economists describe it, a currency peg. It is a remuneration cycle.
The Remuneration Cycle
Let us follow the money, because the chain is specific and its links are deliberate.
This is not a monetary abstraction. This is a wages policy, administered through a currency mechanism, maintained by a treaty that most of the affected populations have never read and were never consulted on. When economists describe the CFA as providing macroeconomic stability, they are technically correct and substantively misleading. The stability it provides is the stability of permanent structural disadvantage: low inflation, yes, but also low wages, low fiscal space and low monetary sovereignty, permanently calibrated to suit a European price level that has nothing to do with life in Ouagadougou or Bamako or N’Djamena.
“The peg does not merely fix the exchange rate. It fixes the value of African labour. Those are not the same sentence. They produce the same outcome.”
The Gold Paradox
Burkina Faso is among the top five gold producers in Africa. Its subsoil holds one of the continent’s most significant mineral endowments. Its workers extract real wealth from real earth. And yet the state that governs them cannot issue a currency that reflects the value of what they produce, cannot set a monetary policy calibrated to their circumstances, and cannot even hold the full proceeds of that production in a reserve account it fully controls.
President Traoré’s call for France to return Burkina Faso’s gold is therefore not merely a rhetorical gesture. It is a statement about the structural relationship between productive sovereignty and monetary sovereignty. A country that produces sixty tonnes of gold per year but cannot issue a currency that reflects that productive base is a country whose sovereignty is incomplete. Not symbolically. Economically. Measurably. In the wages of every worker who extracts that gold and is paid in a currency calibrated in Paris.
Three Countries, One Bank, Zero Sovereignty
The architecture is compounded by its institutional design. The West African Economic and Monetary Union shares a single central bank, the BCEAO, across eight nations: Burkina Faso, Mali, Niger, Senegal, Côte d’Ivoire, Guinea-Bissau, Togo and Benin. The Central African zone has its own equivalent, the BEAC, covering six nations. The result is that fourteen nations, with fourteen distinct economic structures, fourteen distinct commodity endowments, fourteen distinct wage levels and fourteen distinct development trajectories, share two monetary policy frameworks calibrated to a common external peg.
This is not a monetary union in the European sense, where convergence criteria and fiscal transfers at least attempt to address structural divergence. This is a peg imposed by colonial legacy and maintained by treaty inertia, in which Côte d’Ivoire’s cocoa export economy and Niger’s uranium extraction economy and Senegal’s services-led growth are all managed under an identical monetary framework that suits none of them precisely and all of them poorly.
Burkina Faso, Mali and Niger need separate central banks. Not because monetary fragmentation is inherently desirable. But because monetary policy that does not reflect the specific productive reality of the economy it governs is not monetary policy at all. It is monetary administration by a foreign power, dressed in the language of regional cooperation.
“Fourteen nations. Fourteen economic realities. Two central banks. One peg. Set in Paris. This is not monetary union. It is monetary subordination.”
The Panadol: A Gold-Partial-Peg and a Basket of Currencies
The solution is not complicated. It has never been complicated. It is, in fact, straightforward enough that its absence is itself the proof of political obstruction rather than technical impossibility.
Each Sahelian nation, or a genuine voluntary regional bloc negotiated from sovereignty rather than inherited from colonialism, should issue its own currency. That currency should be partially pegged to gold, specifically to the gold that the issuing country physically holds in its own vaults, on its own soil, under its own institutional control. Not hypothetical gold. Not gold held at the Banque de France. Actual gold, auditable, domestically stored, against which a proportion of monetary issuance is anchored.
The gold-partial-peg provides what the CFA claims to provide: monetary credibility, inflation discipline, external confidence. But it provides it against an asset the country actually owns, rather than against a European currency at a rate the country does not set. The basket of trade currencies provides flexibility where the CFA provides rigidity: when commodity prices shift, when drought affects agricultural output, when a new extraction project alters the fiscal position, the exchange rate can move to absorb the shock rather than transmitting it directly into wages and prices.
This is not a radical experiment without precedent. It is the architecture that most serious monetary economists would design if they were designing from first principles for a resource-rich, externally dependent, low-income economy seeking to build domestic productive capacity. The only thing that makes it seem radical is that it has been systematically prevented from being attempted.
Why It Has Not Happened
The answer is not technical. There is no technical reason why Burkina Faso cannot issue a currency partially backed by its own gold. There is no economic law that prevents Niger from establishing a central bank calibrated to its own economy. The IMF will object. France will object. The European Central Bank will issue statements about monetary stability. Bond markets will be cited. Ratings agencies will issue warnings. The full apparatus of international financial credibility will be deployed against the proposition.
But these are political objections dressed as technical ones. The CFA franc system is maintained not because it is optimal for West Africa. It is maintained because it is extraordinarily convenient for France. It provides French firms with a stable, convertible currency environment across fourteen markets simultaneously. It gives French banks a structural advantage in markets where monetary policy cannot be used as a competitive tool. It ensures that African foreign exchange earnings flow through a system in which France retains oversight and, historically, operational control.
When the Sahel juntas expelled French forces, they disrupted the military guarantee of that system. They did not yet dismantle the monetary architecture itself. That is the next frontier. And it is simpler, technically, than any of the military interventions that preceded it. What it requires is not economic sophistication. It requires political will, and the international solidarity to withstand the pressure that will follow its exercise.
The Prescription
The woman who said France is suffering because it can no longer exploit African resources was describing a surface truth. The deeper truth is that the exploitation she was describing was never primarily military or extractive in the crude sense. It was monetary. It was systemic. It was built into the currency through which African workers were paid for the resources they extracted.
Get off the peg. Build your own central bank. Back your currency with your own gold, held in your own vaults. Trade in a basket that reflects your actual partners, not your former coloniser. Set your interest rates to your own wage and price levels. Pay your workers in a currency that reflects the value of what they produce.
This is the panadol for the fiscal headache that the Global South has been nursing since 1945. It is not complicated. It has never been complicated. The question is whether the political will exists to swallow it, and whether the international community of the Global South will stand beside those who do.
The CFA franc does not merely fix the exchange rate. It fixes the value of African labour at a rate calibrated in Paris. A country that mines sixty tonnes of gold per year and cannot issue a currency that reflects that productive base is a country whose sovereignty remains incomplete. Not symbolically. In the wages of every worker who goes underground and comes back up with wealth that is measured, internationally, in a currency someone else controls.
Vayu Putra · The Meridian · October 2026This analysis draws on BCEAO monetary policy frameworks, the 1972 and 1973 CFA franc zone cooperation agreements (as revised), IMF Article IV consultation reports for Burkina Faso, Mali and Niger (2023–2025), World Gold Council production data, Banque de France operations account disclosures, the AidData Franc Zone database, and published scholarship on CFA franc reform including contributions from Ndongo Samba Sylla, Fanny Pigeaud and Bruno Tinel. The monetary architecture proposed draws on historical precedent from managed float regimes and partial commodity-peg systems in comparable emerging market contexts. The Meridian welcomes technical responses from economists, central bankers and policymakers in the franc zone and beyond.
© 2026 The Meridian · themeridian.info · All rights reserved.
Reproduction, redistribution or republication of this article, in whole or in part, without the express written permission of The Meridian is strictly prohibited.
Add comment
Comments